


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
🇺🇸 Producer prices jumped on oil, and the consumer is paying at the pump and little else
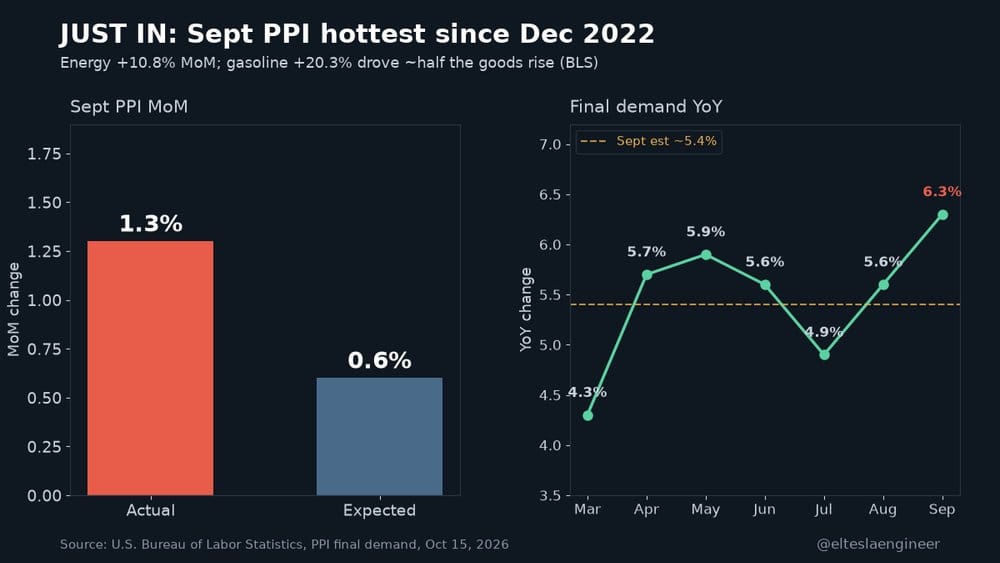
Producer prices rose 1.3% in September against a 0.6% forecast, pushing the annual rate to 6.3% on oil. Retail sales beat at 0.8%, but the control group rose just 0.1% while real wages fell 0.7% on the year.

🇪🇺 Euro area factories are still shrinking, and Lagarde tells Paris the fix is at home
Euro area industrial production fell 0.5% in August, the third straight monthly drop, while inflation reached 3.3% in Germany and 3.1% in France. Lagarde says France has to solve its bond-market problem at home, not through ECB buying.

🇬🇧 UK GDP beat rests on pharma and software, and gilts rallied anyway
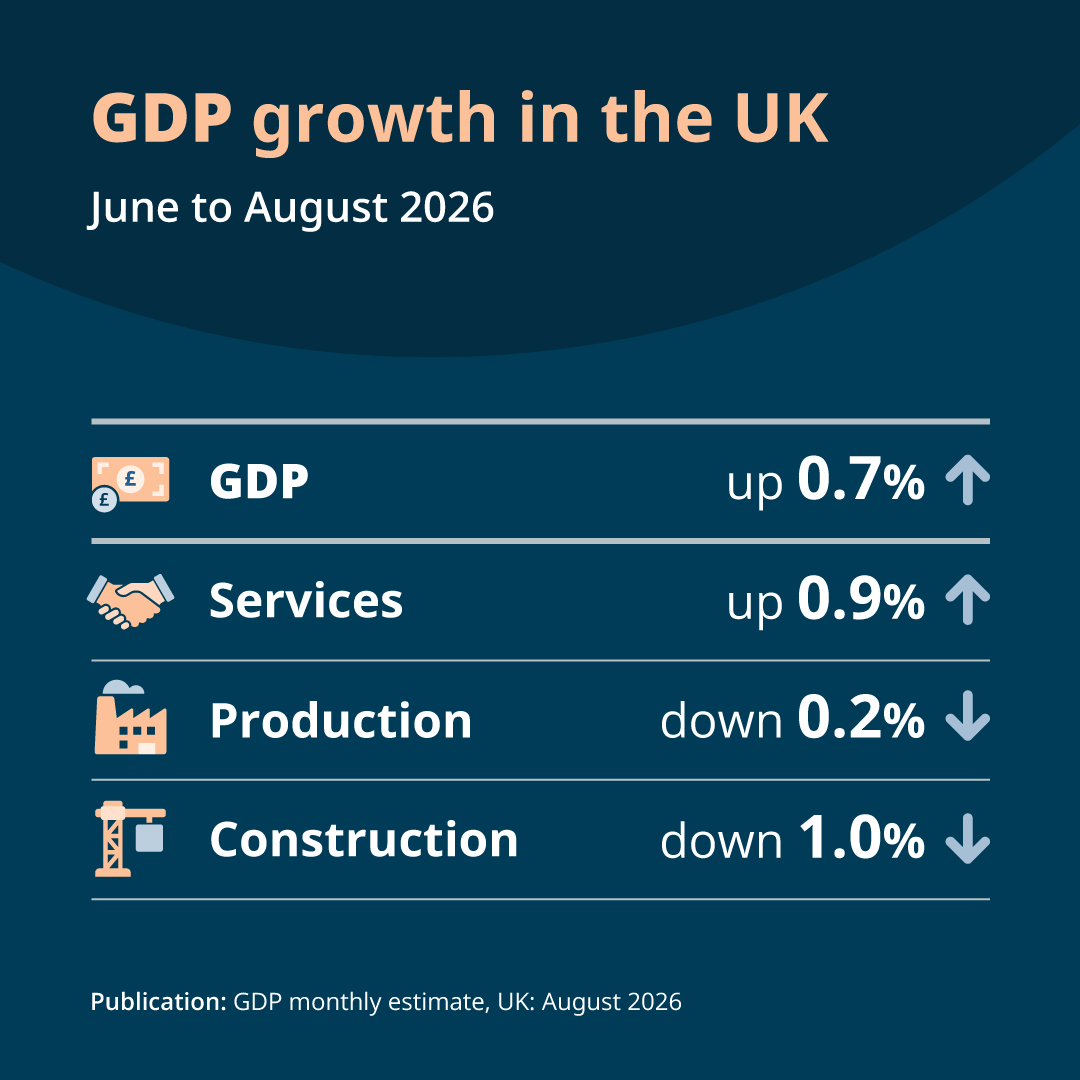
UK GDP rose 0.1% in August against forecasts of a 0.1% fall, carried by pharmaceuticals and software while services stalled. Gilts rallied anyway, with the 10-year yield near 5.32%, as markets pared back Bank of England hike bets to a single November rise.
🌏 Brazil's retail stall gives Copom cover to cut into an oil shock
Brazil's August retail sales rose 0.1% against a 0.7% forecast, handing the central bank cover to cut its 13.75% policy rate in November with Brent near $104. TSMC beat on earnings, and Turkey's budget gap widened.
🇨🇳 China's bond market is betting on weak credit, not 5% factory inflation
M2 growth slowed to an 18-month low of 7.2% and yuan loan growth hit a record-low 4.8%. The 10-year government bond yield fell to 1.65% anyway, a day after factory-gate inflation reached 5.0%.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion