


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
🇺🇸 The Fed is debating a hike into a labor market that's already cracking
Private-sector payrolls rose just 38,000 in August, the slowest since January per ADP, as the Fed weighs a rate hike at its September meeting despite a negative July jobs print and crude oil near $90 a barrel.
🇪🇺 Eurozone inflation jumps to 3.3%, keeping the ECB on track to hike into a cracked recovery
Euro area inflation jumped to 3.3% in August on an energy spike, but core inflation eased to 2.4%. The ECB meets September 10 with markets pricing a hike to 2.50% anyway, on a number it barely controls.

🇬🇧 UK 30-year gilt yields blow past the mini-budget peak, no crisis required
The 30-year UK gilt yield hit 5.89% on Tuesday, its highest since 1998 and above the 2022 mini-budget peak. A global bond sell-off collided with weakening mortgage approvals and a divided Bank of England rate committee ahead of October's Budget.
🌏 Korea's record chip exports just handed the AI capex story its paper trail
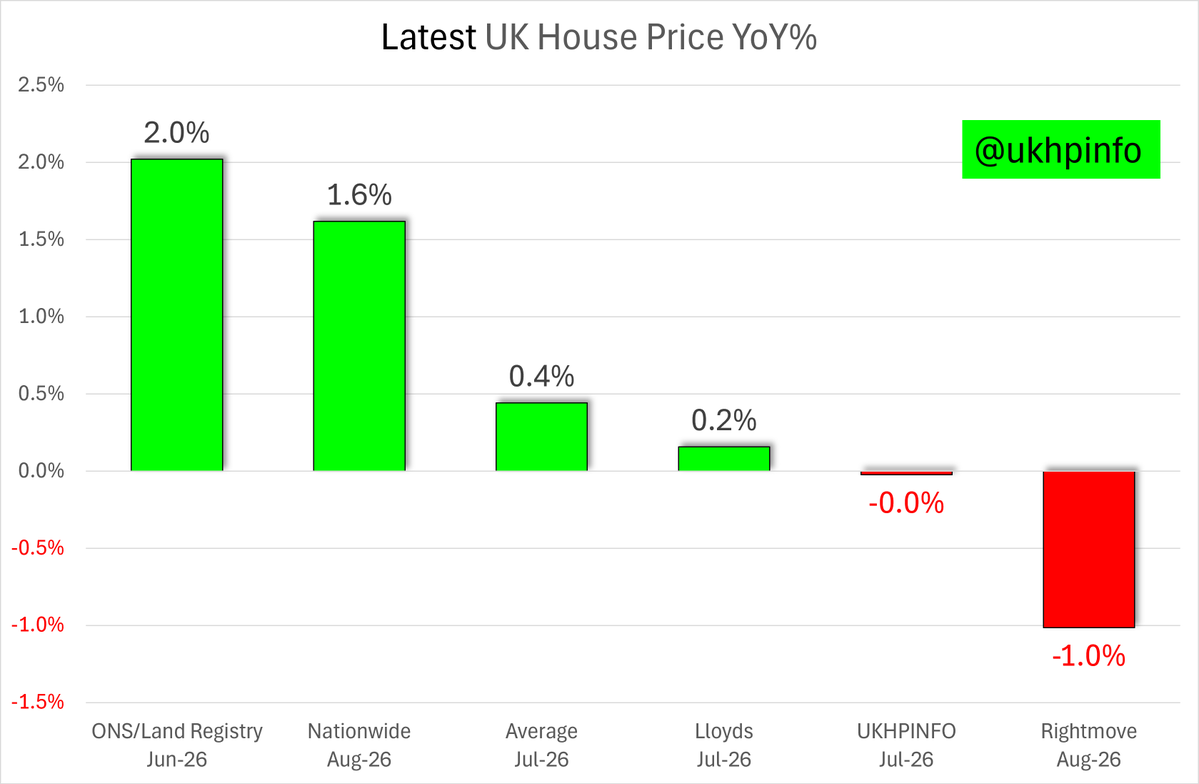
South Korea's chip exports jumped 209% to a record $46.65bn in August, the clearest evidence yet that AI data-center spending is hitting the trade data. Brazil, Turkey and Korea's own sticky inflation show tight money is still biting everywhere else.
🇨🇳 Beijing trades a housing bubble for a housing bust it can control
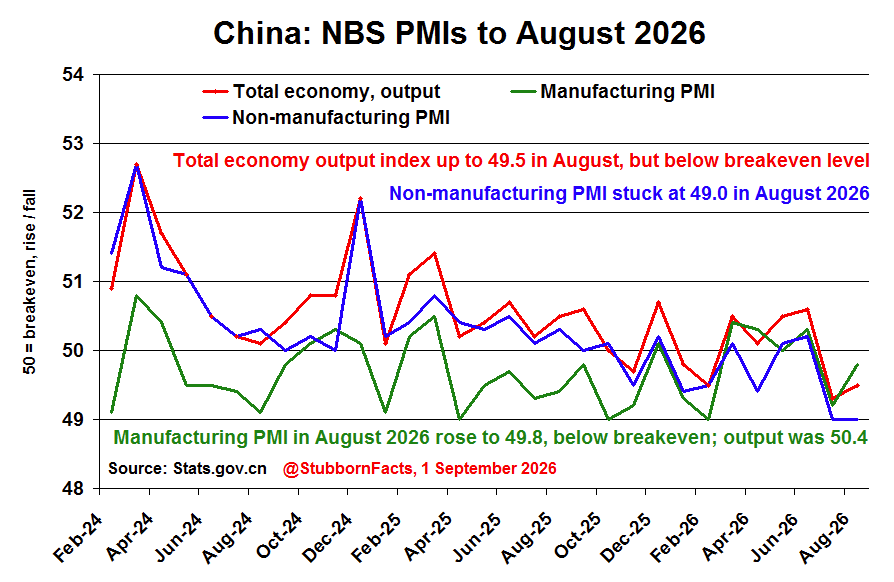
China now requires mortgages to be issued only after homes are completed, and developers paid for it fast: the CSI 300 Real Estate Index fell 4.7% as official and private PMI surveys pull in opposite directions.
That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion