


Welcome to your weekly macro roundup. This comprehensive edition covers the United States, Europe, and key emerging markets with in-depth analysis of the week's most significant economic developments and what they mean for markets ahead.
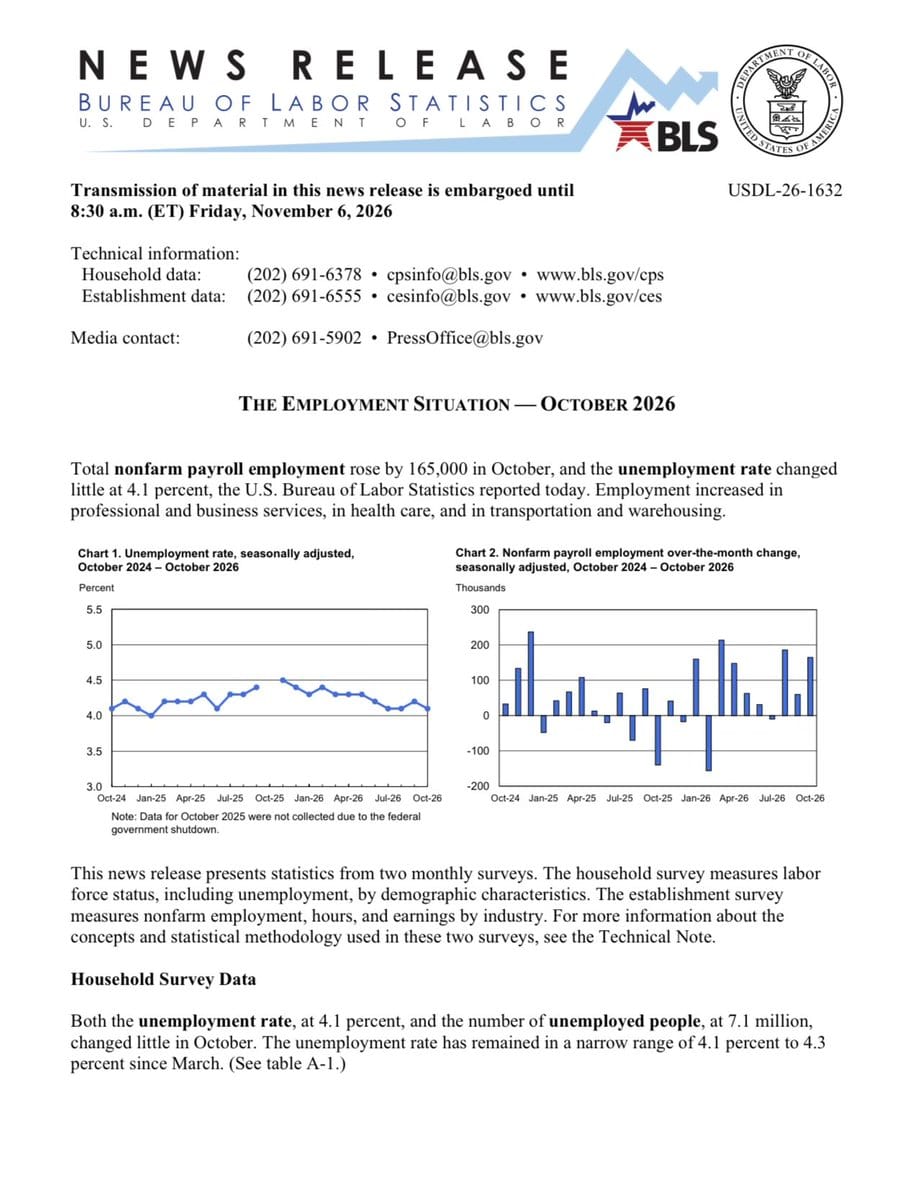
🇺🇸 Payrolls jumped 165,000, and the Fed's case for hiking has stopped depending on wages
US payrolls rose 165,000 in October against a 48,000 monthly average, and traders now price about a 70% chance of a Fed hike on Dec. 9. A record-low labor share and 3.6% productivity growth point to input costs, not wages, as the source of the inflation problem.

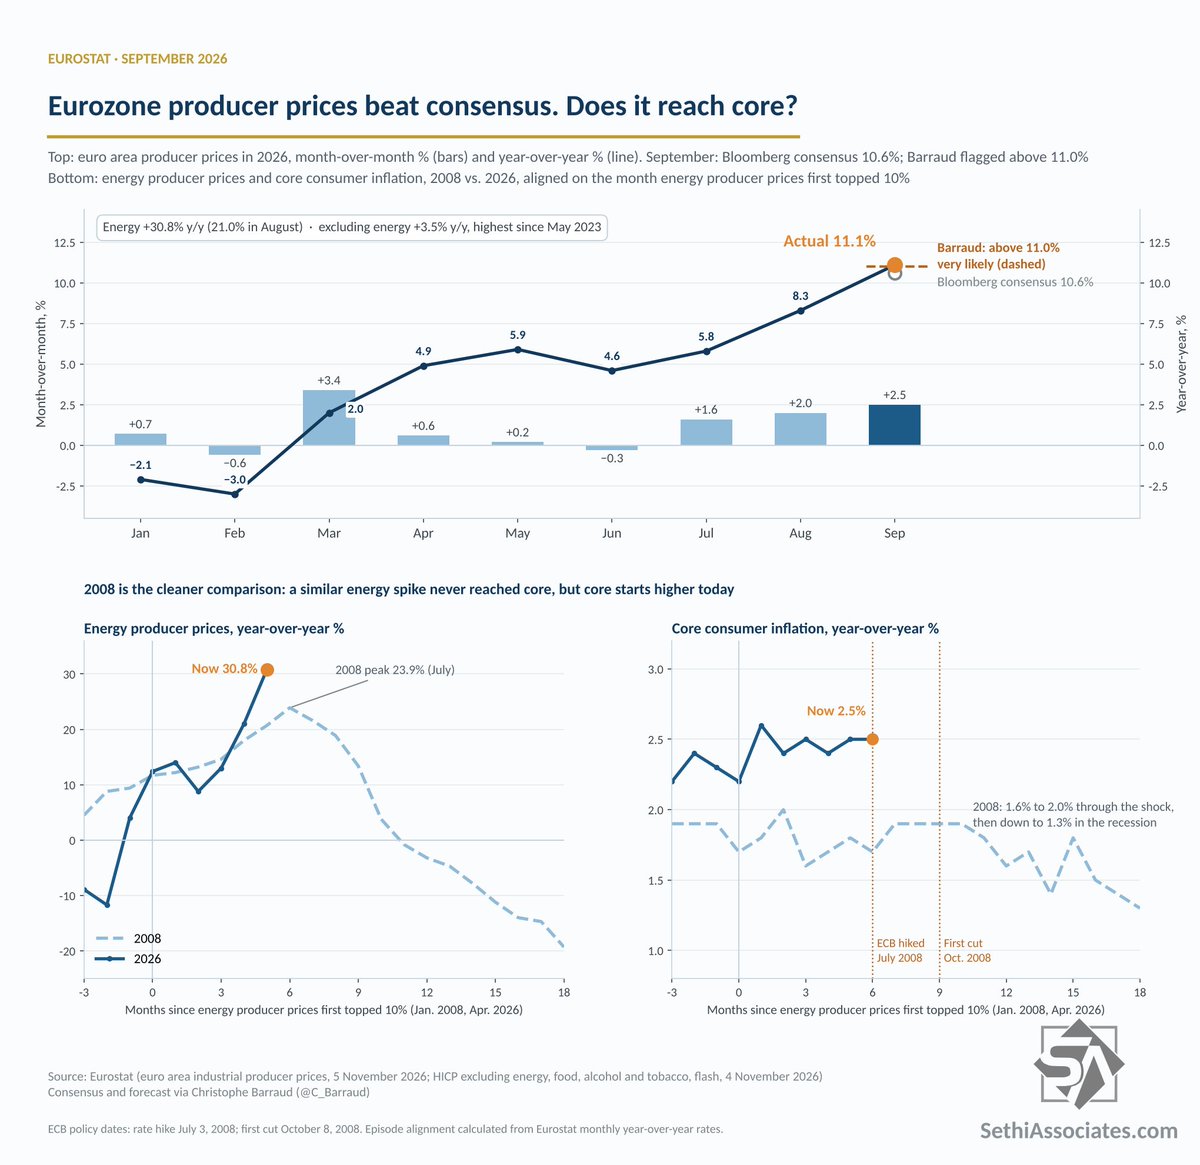
🇪🇺 Energy is lifting inflation and sinking demand, and the ECB must pick a side in December
Euro area inflation rose to 4.0% in October on 20.8% energy inflation, with core steady at 2.5%. Retail volumes fell 0.7% and German volumes 2.0%. Markets price a December European Central Bank hike, and the data before the meeting will decide whether it comes.
🇬🇧 The Bank of England hiked into an upgraded economy, and not one MPC member voted to hold
The Bank of England lifted Bank Rate a quarter point to 4.00% with no one voting to hold and one member seeking a half point, while raising its growth forecasts. Markets put another hike in December at roughly even odds.

🌏 Real rates, not fuel bills, decided who could cut in emerging markets this week
Brazil paused at a 13.75% Selic despite a real-rate cushion of about 9 points, Mexico cut to 6.25% on a split vote, and the Czech central bank hiked to 4.00%. One fuel shock, three different answers.

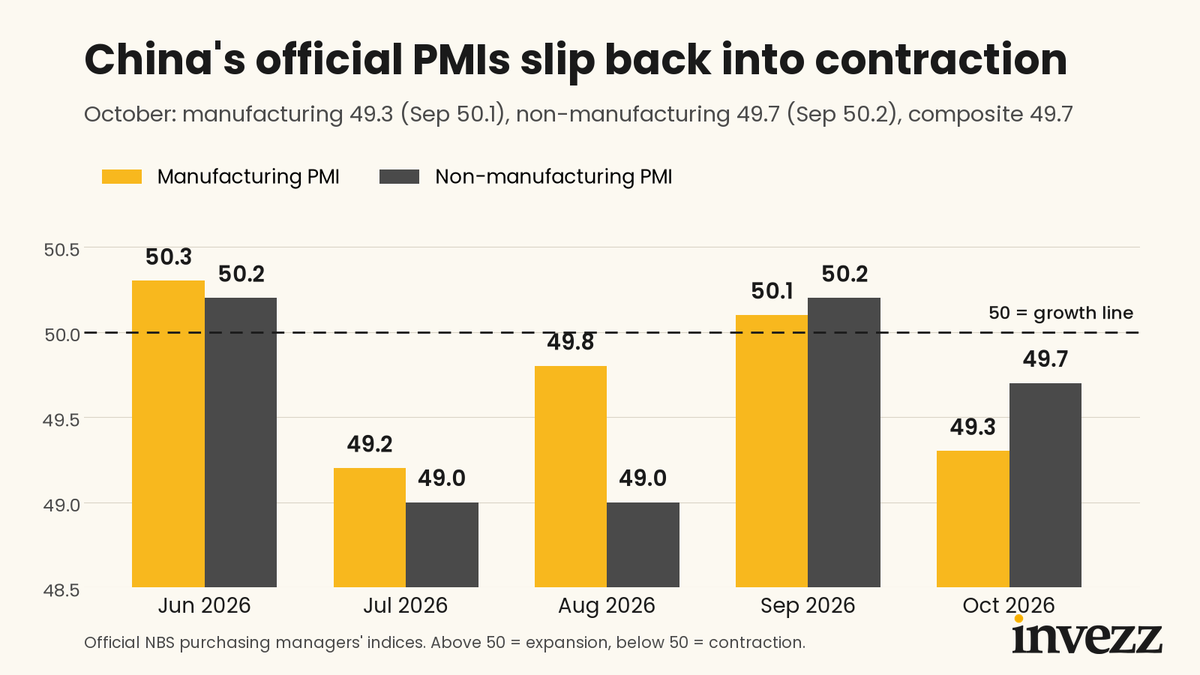
🇨🇳 Beijing lowers the funding floor quietly, leans on the yuan and asks firms to buy their own shares
The PBOC made a 1.25% overnight reverse repo its main policy rate, lifted the FX reserve requirement to 6% to slow the yuan and added CNY100bn of stock support, with the official manufacturing PMI down at 49.3.
That wraps up this week's macro roundup. We'll be back with daily updates throughout the week and another comprehensive weekly edition next time. If you know someone who would appreciate this analysis, feel free to share. More signal, less noise, as ever. Cheers.
Discussion