


Welcome to your weekly macro roundup. This comprehensive edition covers the United States, Europe, and key emerging markets with in-depth analysis of the week's most significant economic developments and what they mean for markets ahead.
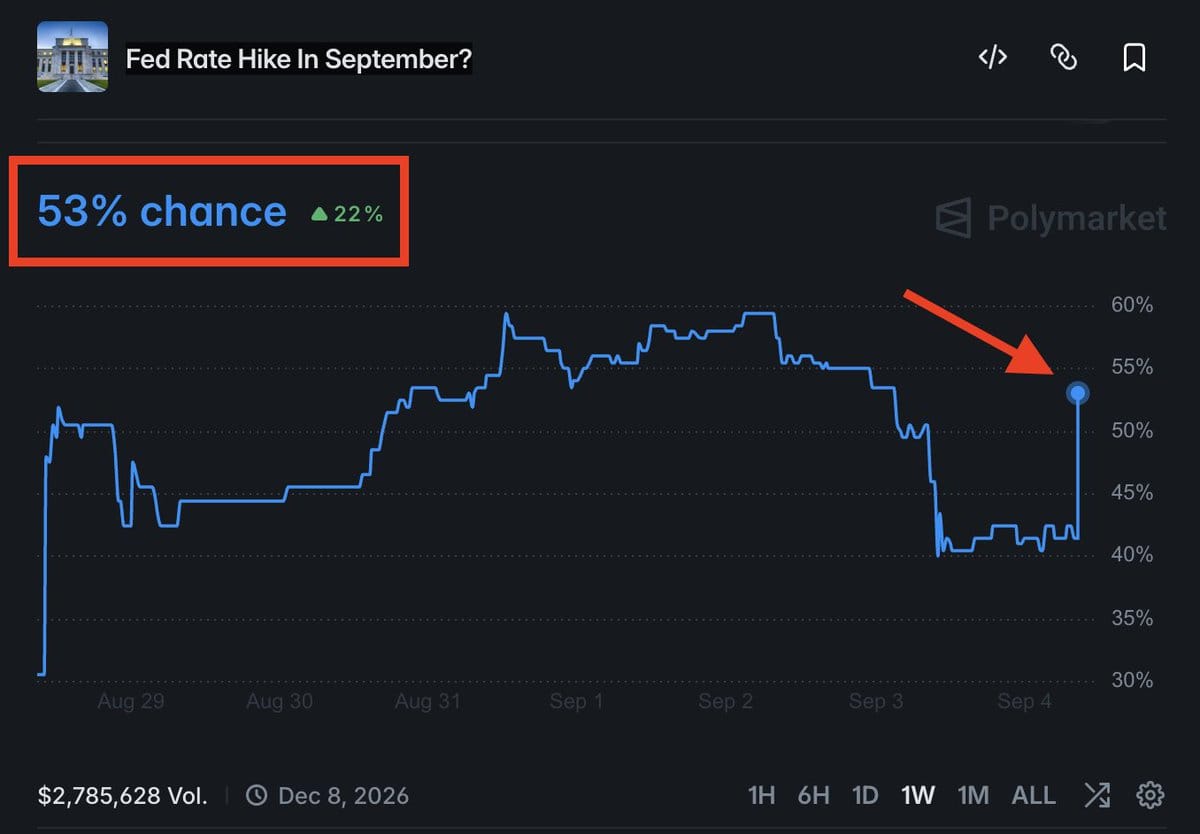
🇺🇸 A Fed with no reaction function heads into September's meeting
Payrolls jumped to 162,000 in August just as ISM services and manufacturing price gauges hit their highest levels since 2022. Fed governors are now publicly split over a September move, with hike odds swinging from 35% to 61% in a week.

🇪🇺 Germany's export orders return after four years, just as the ECB prepares to hike into a fractured eurozone
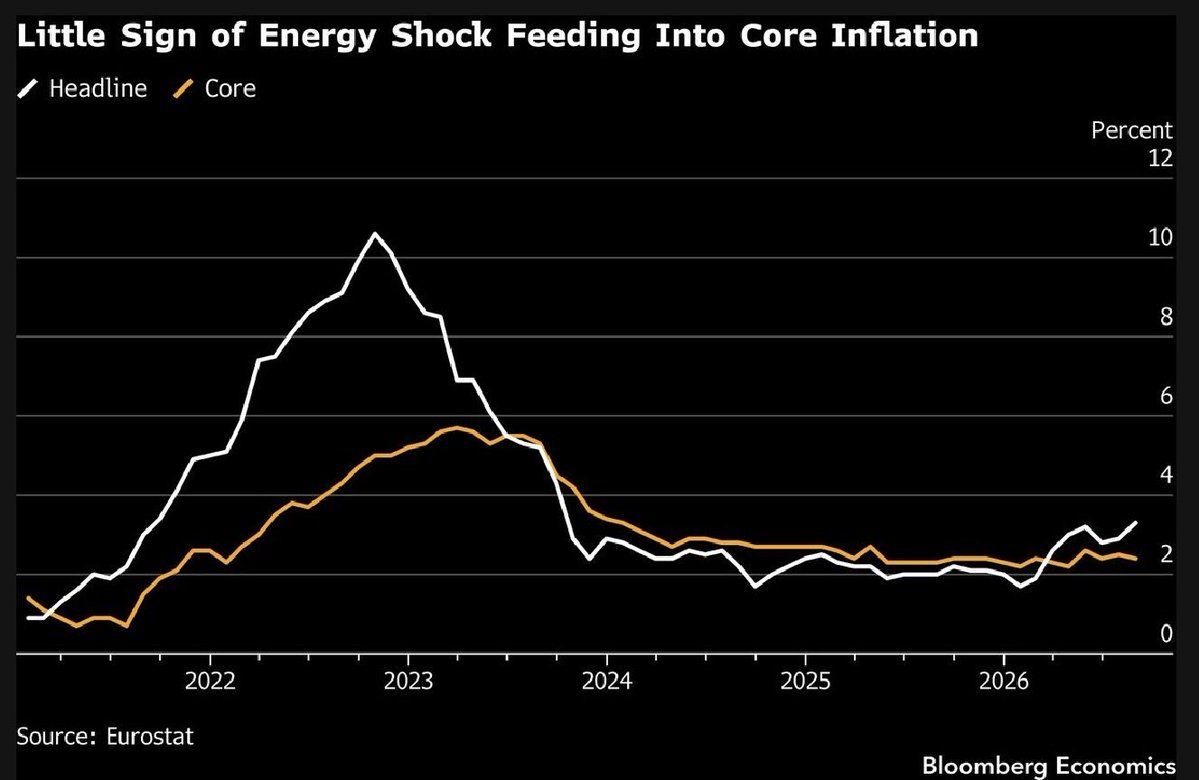
Eurozone headline inflation jumped to 3.3% in August on energy costs while core inflation cooled to 2.4%, setting up a widely expected ECB hike to 2.50% on September 10 even as Germany's export orders turn positive for the first time in over four years and French yields spike to 4.23%.
🇬🇧 UK's data is split enough that hawks and doves can both claim vindication before September 17
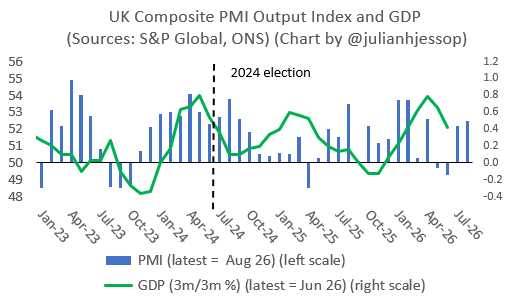
The Bank of England is split ahead of its September 17 decision. UK services activity hit a four-month high, construction extended a 20-month contraction, and headline inflation rose to 2.9% on energy costs. The case for either a hike or a hold just got harder to make.
🌏 Asia's central banks have stopped answering to inflation alone
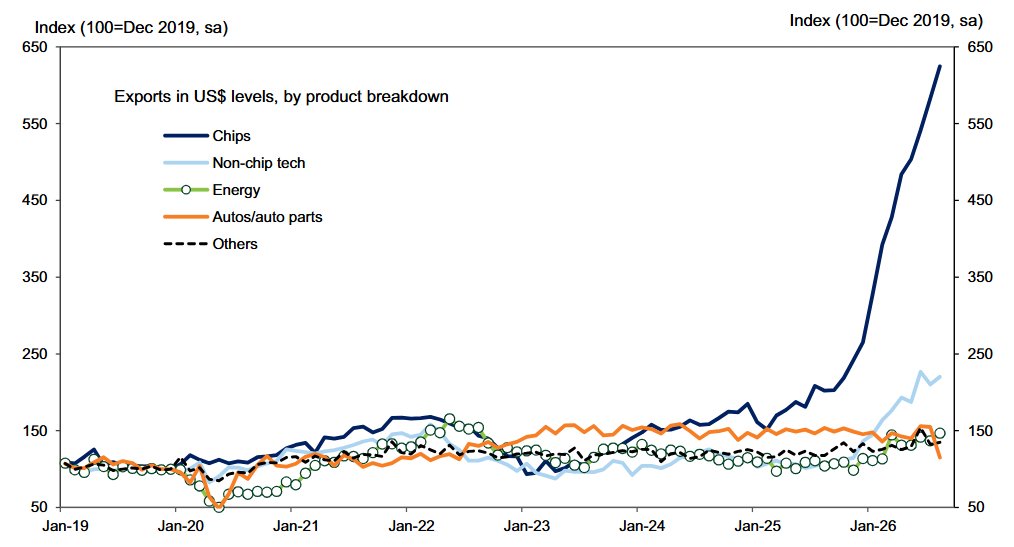
South Korea hiked to 3.00% to cool Seoul housing debt even as chip exports surged 68.7%. Brazil, Turkey and South Africa held steady instead, part of a broader emerging-market split as capital flows extend an eighth straight week of inflows.
🇨🇳 For the first time in years, China's currency problem is strength, not weakness
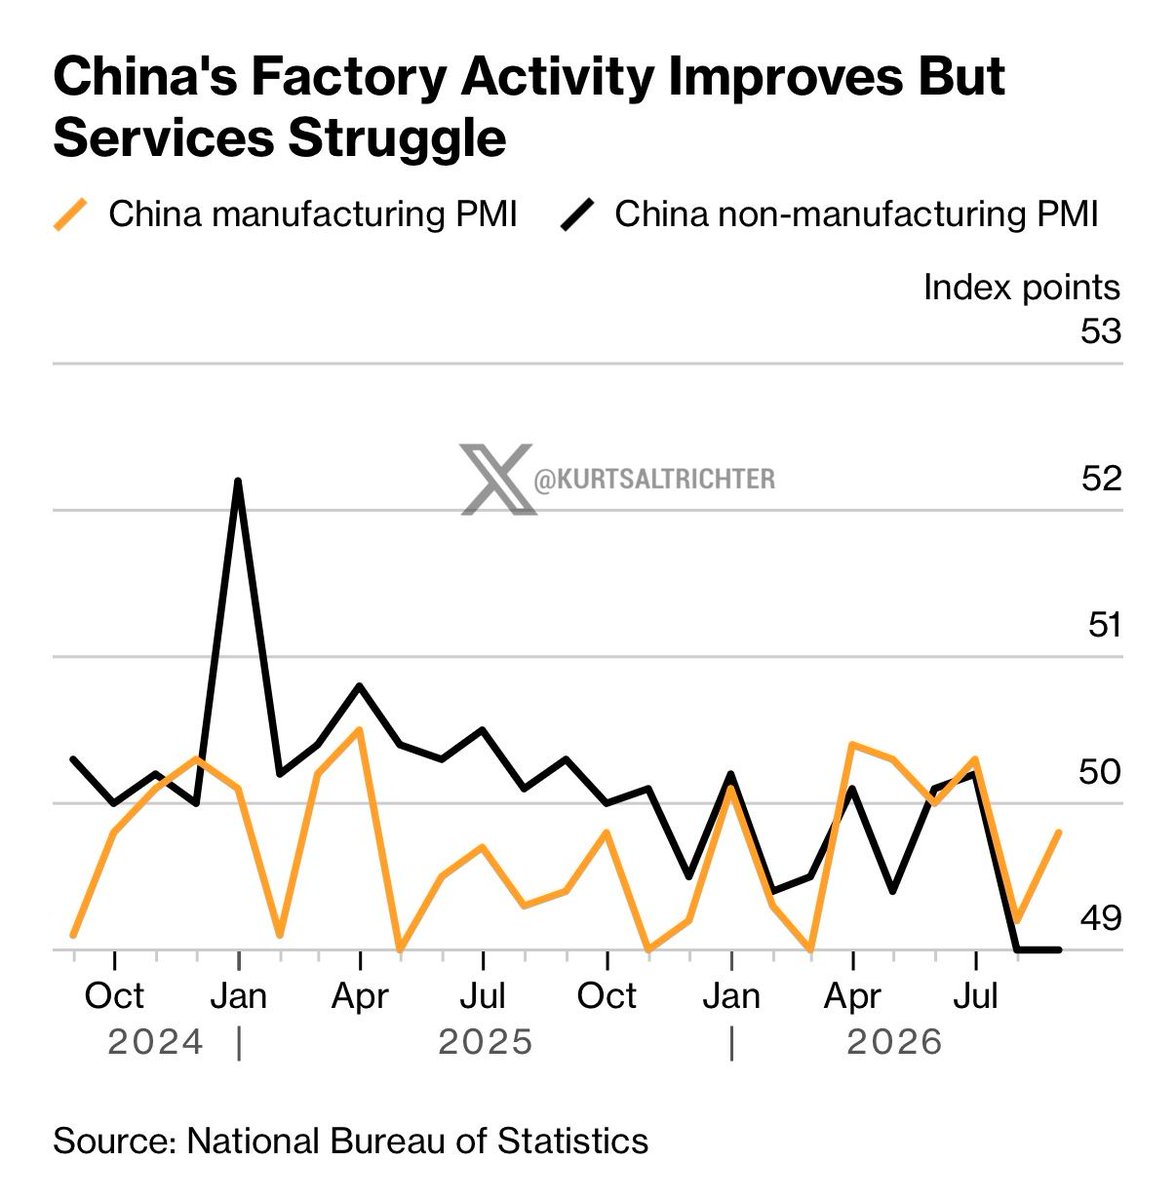
The PBOC set its yuan fix 694 pips weaker than markets expected and drained ¥1.41tn in liquidity to slow the currency's climb to a three-year high. Factory data tell two stories: a state-heavy sector still contracting, a private export sector expanding for a ninth straight month.
That wraps up this week's macro roundup. We'll be back with daily updates throughout the week and another comprehensive weekly edition next time. If you know someone who would appreciate this analysis, feel free to share. More signal, less noise, as ever. Cheers.
Discussion