


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
🇺🇸 If Warsh holds, dissents and core PCE will do the talking
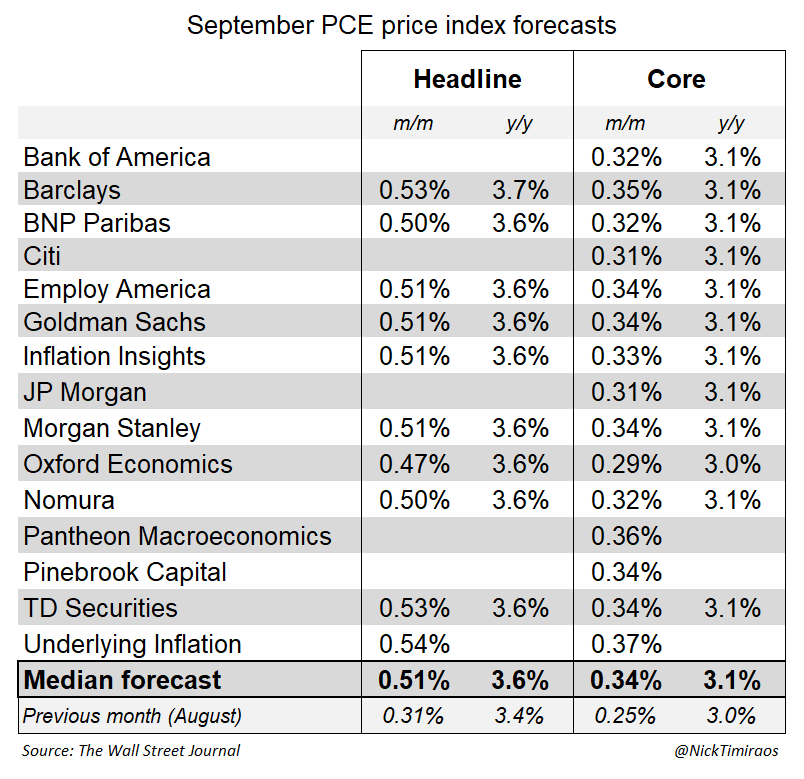
A hold at 3.75% to 4.00% is the base case today, which leaves dissents and statement wording to carry the message. Core PCE is forecast at 3.1% on Thursday, after producer prices jumped 1.3% in September.

🇪🇺 Euro area inflation is mostly energy, and demand is already buckling
Spain's producer prices rose 18.3% and Italy's 13.8% in September, almost all of it energy, while French household confidence hit its lowest since 2013. The European Central Bank meets Thursday with rates expected to hold at 2.50%.

🇬🇧 Healey spends fiscal headroom on energy bills while the Bank of England leans toward a hike
Chancellor John Healey's Budget cut household energy bills and left £15bn of headroom, down from £23.6bn. With the 10-year gilt yield near 5.32% and September CPI at 3.5%, a Bank of England hike on 5 November is still in play.

🌏 Korea's chip boom is lifting exports and incomes, but households are not seeing it
Chip prices pushed South Korea's real national income up 18.8% year-on-year, while third-quarter GDP grew 1.0% on the quarter, ahead of the 0.7% forecast. From Malaysia to Mexico, AI hardware exports boomed as household confidence and consumption weakened.

🇨🇳 China's banks max out the central bank's overnight window while the policy rate stays put
Banks drew the central bank's full CNY1tn overnight reverse repo ceiling for a second day with the 1.40% policy rate untouched. The five-year government bond yield hit a record 1.34%, and weak yuan fixings are leaning against appreciation.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion