


Welcome to your weekly macro roundup. This comprehensive edition covers the United States, Europe, and key emerging markets with in-depth analysis of the week's most significant economic developments and what they mean for markets ahead.
🇺🇸 Fed hawks are talking half-point hikes, but bonds are rallying and stocks have slipped into correction
Fed Governor Waller wants a half-point hike in December, yet the 10-year Treasury yield fell more than 13 basis points to 4.92% and the S&P 500 slid into correction. The market is pricing growth risk, not inflation.

🇪🇺 Euro area inflation is at 4%, and the ECB's December hike is about to meet the fiscal limit
Euro area inflation was confirmed at 4.0% in October, with energy at 21.0%, and a European Central Bank hike to 2.75% in December looks likely. The Commission's projections of wider deficits and rising interest bills are the obstacle.

🇬🇧 The fuel shock has reached the UK Treasury before it has reached CPI, and index-linked gilts are the channel
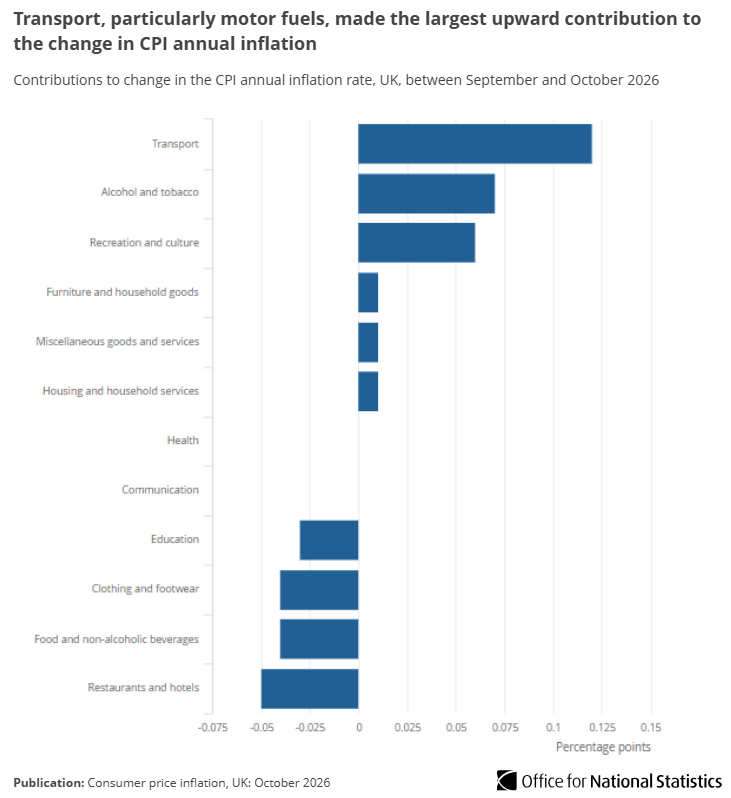
UK government debt interest hit £11.2bn in October, a record for the month, with £4.2bn from the inflation uplift on index-linked gilts. CPI of 3.6% undershot forecasts, but record diesel prices keep a December Bank of England rate rise in play.
🌏 Emerging markets are splitting in two, with AI hardware on one side and a 103.89 dollar index on the other
The Taiex fell a record 17.5% this week while Korean exports passed $1tn. With the dollar index at 103.89, Bank Indonesia hiked to 6.00% and the South African Reserve Bank held at 7.25% as inflation jumped to 5.2%.

🇨🇳 China's frozen loan rate subsidizes factories and squeezes households
The PBOC held its one-year loan prime rate at 3.0% for an 18th month as October retail sales rose just 0.4% and producer prices rose 5.7%. Real borrowing costs are negative for factories and near +5% for homebuyers.

That wraps up this week's macro roundup. We'll be back with daily updates throughout the week and another comprehensive weekly edition next time. If you know someone who would appreciate this analysis, feel free to share. More signal, less noise, as ever. Cheers.
Discussion