


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
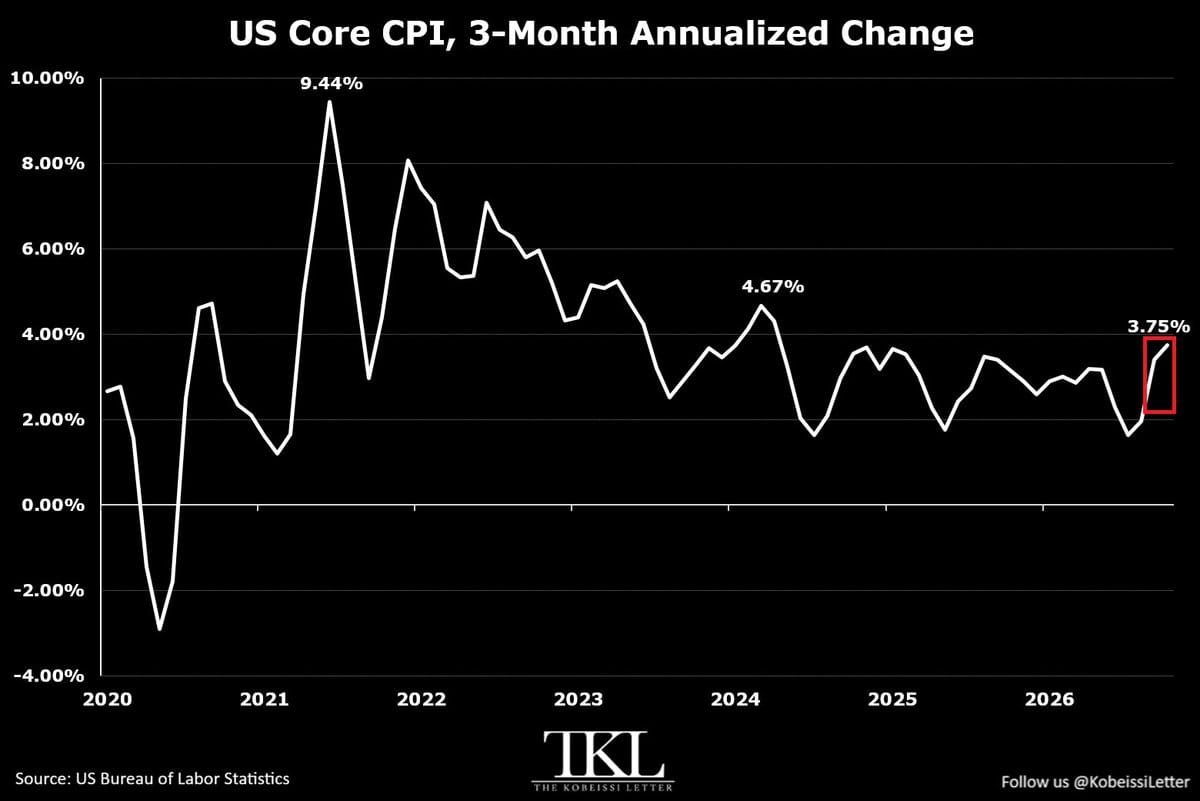
🇺🇸 Fed heads into a December hike with no 12-month CPI to point to
October CPI rose 0.4% against a 0.3% forecast, core came in at 0.3%, and the two-year Treasury yield jumped 17.6 basis points. Futures fully price a December Fed hike, with an 11.5% chance of a half-point move.

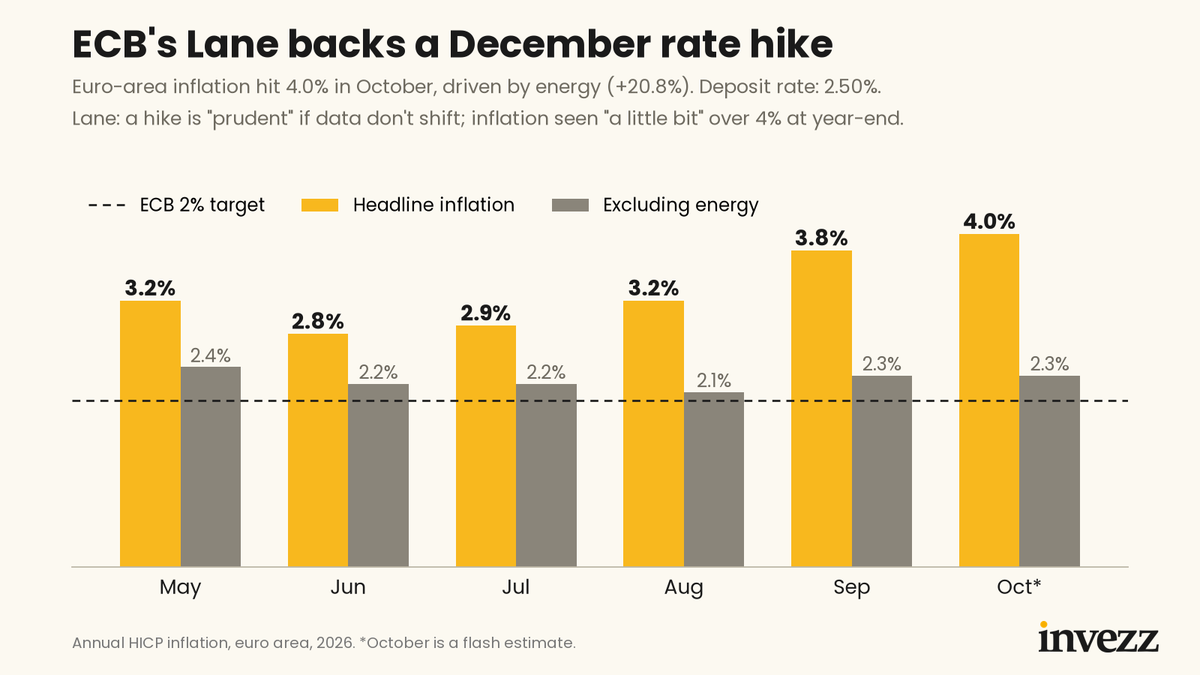
🇪🇺 Berlin's growth upgrade takes away the ECB doves' best argument
Germany's Council of Economic Experts raised its 2026 growth forecast to 1.3% from 0.5%, which takes the growth argument away from ECB doves. All 71 economists in a Reuters poll already expect a December hike to 2.75%.
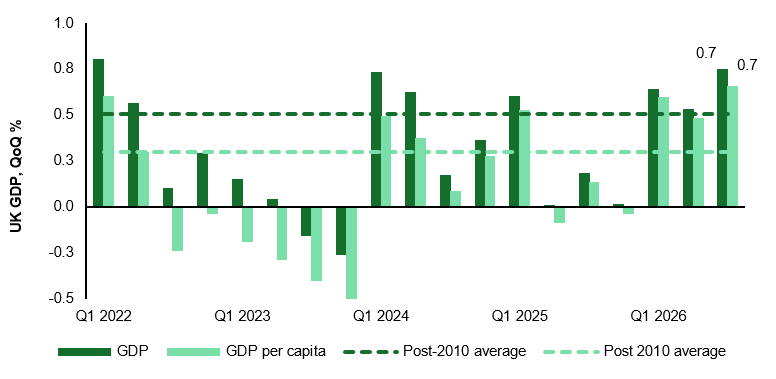
🇬🇧 A narrow slice of the UK economy delivered 0.7% growth, and the Bank of England is tightening anyway
UK GDP rose 0.7% in Q3, as forecast, but services and a narrow tech-led cluster did the lifting while hospitality and construction shrank. Markets price about 76% odds of a December Bank of England hike ahead of next week's jobs and inflation data.
🌏 India's inflation breaks through 6% even after an RBI hike, while Turkey and Indonesia lose ground
India's consumer inflation hit 6.09% in October, through the RBI's 6% ceiling despite its October rate hike. Turkey's central bank lifted its 2027 inflation forecast to 21%, and Indonesia's rupiah fell to a record low of 18,248 per dollar.

🇨🇳 China's trade surplus shrank because exports cooled and imports got pricier, not because demand recovered
October's surplus fell to $105.28bn, but the 41.6% jump in imports owes more to base effects and commodity prices than to demand. Consumer inflation of 0.7% and falling domestic car sales say the home market is still weak.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion