


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
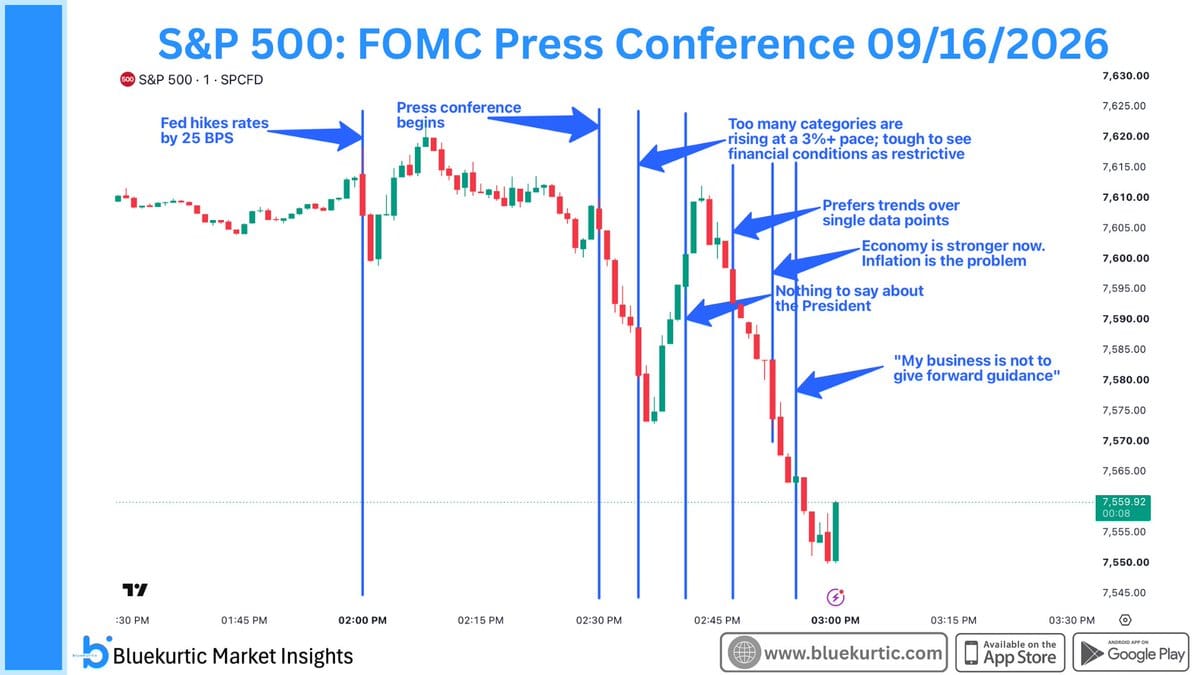
🇺🇸 The Fed hiked and then told markets it isn't done
The Fed raised rates 25 basis points to 3.75%-4.00%, unanimously, and penciled in another hike to roughly 4.1% by year-end. The Atlanta Fed's GDPNow nowcast jumped to 5.1% even as housing starts and homebuilder sentiment kept sliding.

🇪🇺 Europe's trade surplus is quietly collapsing while inflation data stays calm
The euro area's January-July trade surplus collapsed 82% to €17.0bn from €92.8bn, even as headline inflation held at 3.2% in August. German wholesale prices and Spanish bond yields point to an energy-driven strain the calm inflation print is hiding.

🇬🇧 BoE holds at 3.75%, but gilts cared more about QT than CPI
The Bank of England held Bank Rate at 3.75% in a 6-3 vote on 16 September as UK inflation hit 3.1% on an energy shock. Gilt yields moved more on the plan to shrink the Bank's bond holdings to zero by 2034 than on the inflation print itself.

🌏 Taiwan and Singapore shrug off the Fed as AI exports boom
The Fed hiked to 3.75%-4.00% on Wednesday. Taiwan held for a tenth straight quarter and lifted its 2026 GDP forecast to 11.48%, Singapore's non-oil exports jumped 46.2% on AI-linked demand, Brazil cut, and India's central bank ran its first bond sale since 2017.

🇨🇳 China's property slump has become a jobs problem, not just a price one
China's August data: industrial output up 5.2% year-on-year, but youth joblessness (ages 16-24) at 18.9%, tying its worst reading. New bank loans nearly stalled at ¥60bn against forecasts of ¥400-420bn, and real estate investment fell 19.9%.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion