


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
🇺🇸 Waller's disinflation bet meets a hot services prices print
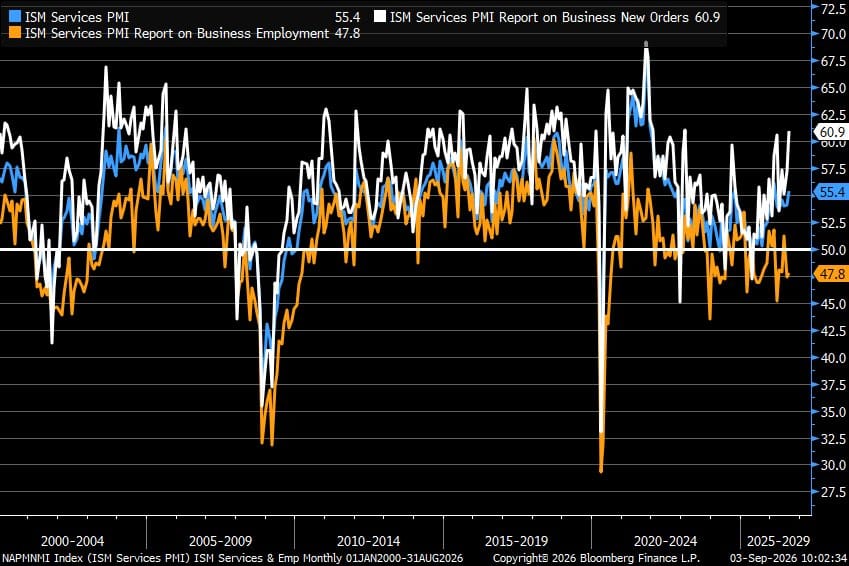
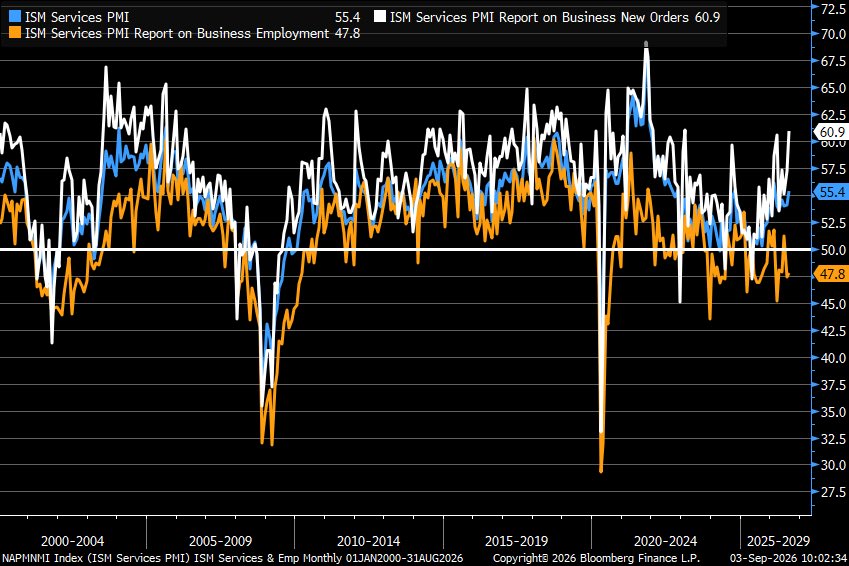
Fed governor Christopher Waller said he'd back holding rates at 3.50%-3.75% in September if inflation data cooperates. Hours later, the ISM's services prices index jumped to 72.6, the highest reading since August 2022.
🇪🇺 France's borrowing costs jump as the ECB hikes into a cooling core
France's 10-year bond yield jumped to 4.23% at Thursday's auction, up from 3.86%, even as euro area core inflation cooled to 2.4% ahead of the European Central Bank's September 10 decision, where a quarter-point hike to 2.50% is already fully priced.

🇬🇧 UK gilt yields hit 2008 levels as an oil shock guts Healey's Budget room
UK 10-year gilt yields hit 5.29%, the highest since 2007-08, and 30-year yields touched 5.92% after a US-Iran flare-up pushed Brent crude above $94 a barrel. Chancellor John Healey's Budget headroom is now squeezed to an estimated £13-14bn ahead of October 28.

🌏 India's $136bn haul looks like insurance, not rescue
India's central bank raised $136.4bn via a dollar deposit scheme, nearly five times its 2013 crisis-era haul, banking room to manage rates without hurting the rupee. Brazil, South Africa and Mexico show diverging emerging-market policy paths ahead of September meetings.

🇨🇳 China's services rebound can't paper over Hong Kong's slide back into contraction
China's services gauge jumped to 51.4 in August while the official factory survey stayed below 50, and Hong Kong's PMI slid back into contraction at 49.5. The PBOC drained roughly ¥469bn from money markets anyway, holding lending rates unchanged.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion