


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
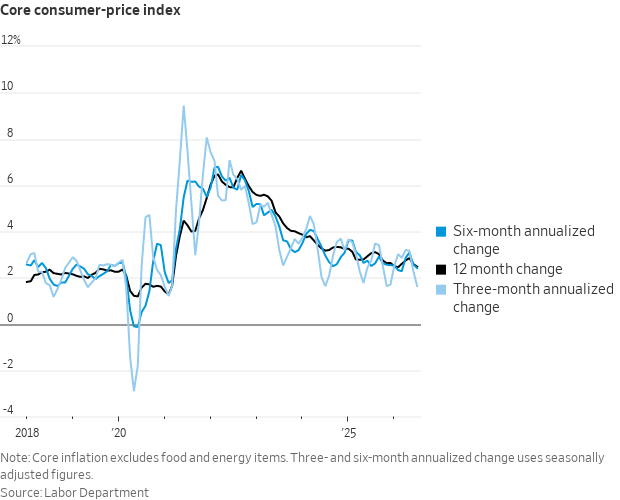
🇺🇸 Core CPI cools to 2.5%, but goods prices just came back to life
US core CPI eased to 2.5% year-on-year in July, but core goods prices posted their largest monthly gain since September 2025, an early hint of tariff pass-through that complicates the Fed's easing path.

🇪🇺 German inflation jumps to 2.8% and boxes in the ECB's rate pause
German consumer prices jumped 2.8% year on year in July, above forecasts, while Italy's harmonised inflation hit 2.9%. The ECB held rates steady anyway, even as Eurozone Q2 growth beat expectations at 0.4% quarter on quarter, complicating the case for cuts.

🇬🇧 Three BoE policymakers voted to hike, not cut, in July
Three Bank of England policymakers voted for a hike, not a cut, in a 6-3 split that held Bank Rate at 3.75% on 30 July. It's an unusually hawkish dissent that raises the stakes for September, with flawed labour-market data leaving the committee without its usual anchor.

🌏 EM central banks are pulling apart, not just from the Fed
India's CPI cooled to 4.45% but stayed above target, Brazil's services growth accelerated as its central bank kept cutting rates, and South Korea's jobless rate held near full employment. Three separate inflation stories, not one EM narrative.

🇨🇳 China's producer deflation streak outlasts the 2015-16 commodity bust
China's factory-gate prices fell −3.5% year-on-year in July, marking 34 consecutive months of producer deflation, longer than the 2015-16 commodity bust, even as several outlets misreported the figure with the wrong sign.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion