


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
🇺🇸 Hammack's case for more hikes rests on factory orders, not core CPI
Cleveland Fed President Beth Hammack says rates are not yet high enough and that higher yields are no substitute for hikes, citing shop-floor demand. The 10-year Treasury yield ended Friday at 5.24% ahead of Wednesday's September CPI, where headline is forecast at 0.6%.

🇪🇺 Euro bills rally, but the ECB signals no backstop for France
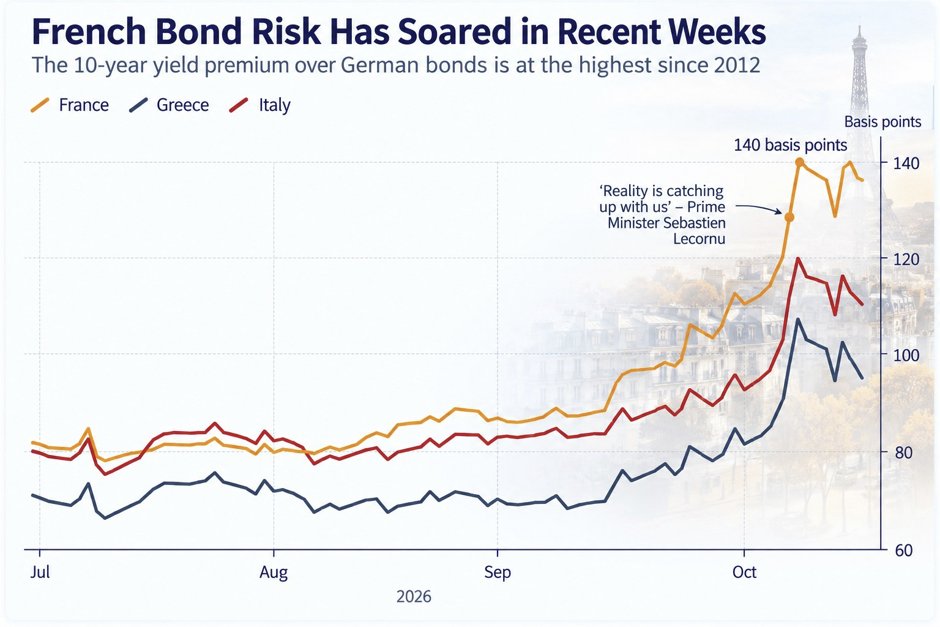
France's 10-year spread over Bunds widened to 141.5 basis points as ECB officials reportedly see no case for their anti-fragmentation tool. German bill yields fell, and markets price a December rate hike.
🇬🇧 A weak August GDP print won't help gilts
August UK GDP is expected to fall 0.2% after July's 0.4% gain. With the 10-year gilt near 5.5% and the 30-year above 6%, a weak print adds to fiscal strain before the 28 October Budget instead of bringing relief.

🌏 Rates can't carry India's rupee any more, so the RBI has turned to plumbing
India's inflation hit 5.54% in September, a 23-month high, and the real policy rate is slightly negative. The Reserve Bank of India answered with dollar sales for oil refiners and curbs on rupee speculation, and the rupee closed at 95.75 per dollar.
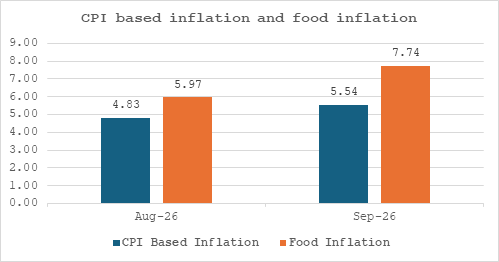
🇨🇳 China's yuan is firming while its car buyers retreat
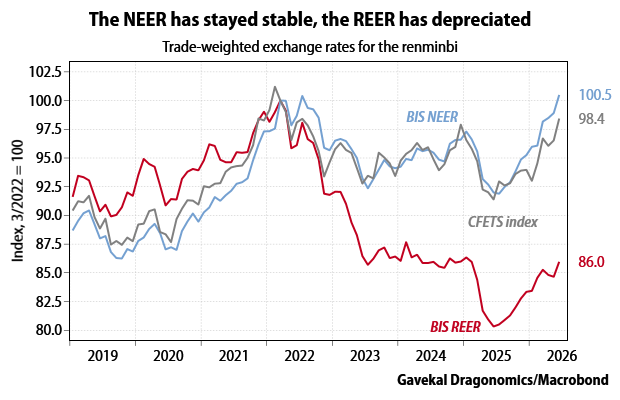
China's central bank set the yuan's daily fix at 6.7313, the firmest since early 2023 but still 336 pips weaker than models implied. September car retail sales fell 28.0% year on year while passenger-vehicle exports jumped 73.7%.
That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion