


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
🇺🇸 Fed's October bet turns on a speech, not Wednesday's cooler PCE
Core PCE cooled to 3.0% year over year on Wednesday, but October rate-hike odds barely moved until New York Fed's John Williams urged patience. Fed Governor Michael Barr says the data still call for more hikes.
🇪🇺 Europe's factory floor is roaring back, right as France's bonds flash 2012
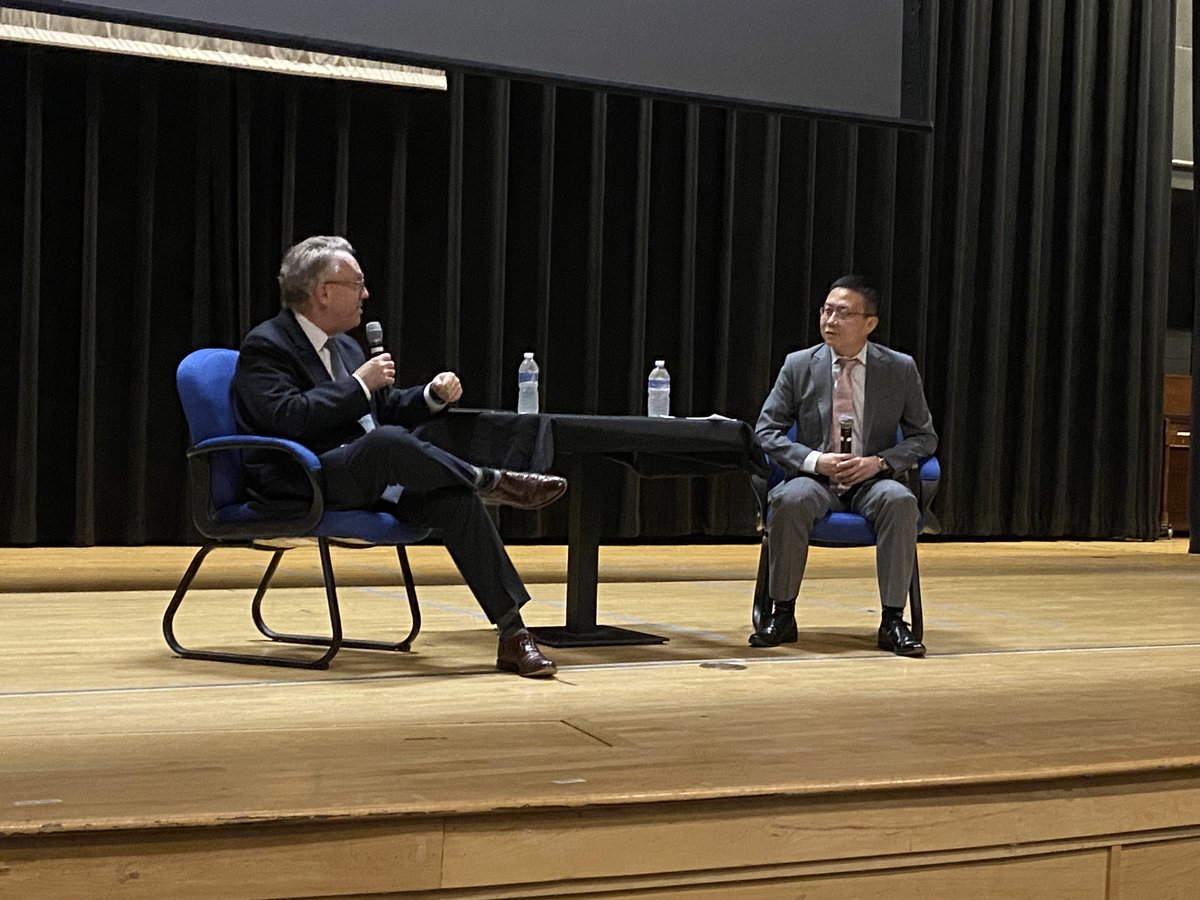
Eurozone manufacturing PMI hit 52.9 in September, the first time all eight surveyed member states have expanded at once in over four years. Inflation accelerated at the same time, and the French-German bond spread widened to levels last seen in the 2011-2012 debt crisis.
🇬🇧 Bailey warns on an AI bubble as Mann pushes the Bank of England toward a November hike
Catherine Mann wants a November hike to 4.00% Bank Rate. Andrew Bailey is just as focused on a global AI investment boom, now near $450bn in debt issuance, that poses risks the Bank can't price or control.
🌏 Colombia hikes into stagflation while Korea's chip boom hides a factory slump
Colombia raised rates 25 basis points to 12.25% on a split 4-2-1 vote with unemployment at 9.4%, while South Korea posted record chip-driven exports of $120.9bn next to its steepest industrial output drop since 2008.

🇨🇳 China's PMIs just cleared 50. The real policy shift is the mortgage subsidy
China's factory surveys cleared 50 in September, but the real story is Beijing's first-ever nationwide mortgage subsidy, launched alongside a cut to a policy-bank lending rate. Factory employment is still stuck below 50.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion