


Good morning, macro enthusiasts. Here's your daily roundup covering the United States, Europe, and key emerging markets. We cut through the noise to deliver the essential facts, key surprises, and meaningful context from each region in one place.
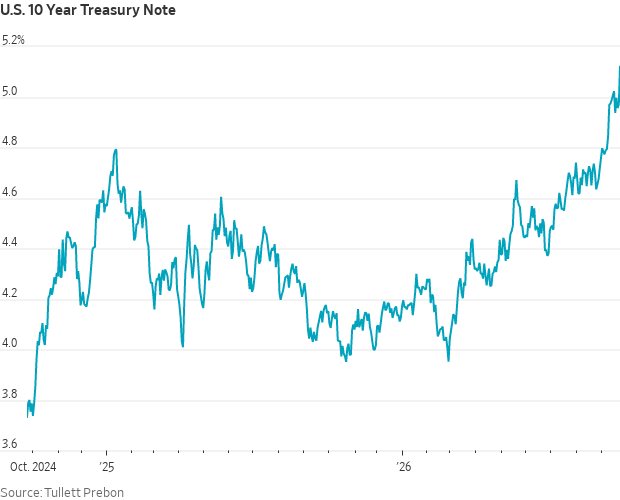
🇺🇸 Washington's interest bill just crossed $1tn, and the bond market is sending the receipt
US net interest payments on the federal debt topped $1tn for fiscal year 2026, a first, in the same week the 10-year Treasury yield hit 5.11%, its highest since July 2007, and the White House pushed the Fed to ease policy.
🇪🇺 Germany's own forecasters just broke the disinflation script for 2027
Germany's five leading economic institutes now see inflation accelerating to 3.2% in 2027, not fading. ECB officials trace the persistence to war-damaged refining capacity that will take years to rebuild.

🇬🇧 The BoE's dovish wing turns hawkish just as UK growth slows
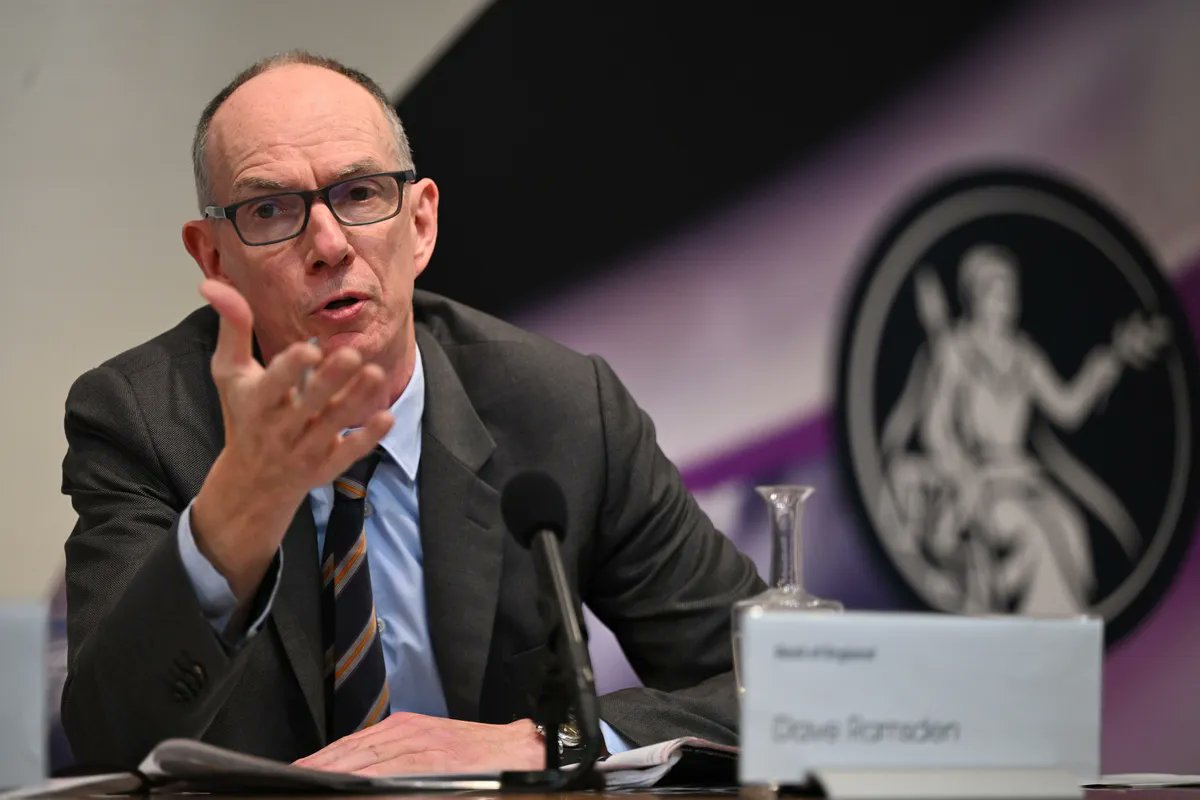
Dave Ramsden just became the third Bank of England policymaker in a week to flag hawkish inflation risk, right as UK business surveys roll over, including a retail sales survey at its weakest since 1983. November's hike is looking more live.
🌏 India's factories are humming, and the RBI is about to hike anyway
India's industrial output grew 8.0% year-on-year in August. Markets are pricing a Reserve Bank of India hike in October anyway, as Brent crude nears $107 a barrel. Brazil's central bank cut rates into a surprise inflation spike two weeks before its election.
🇨🇳 China's tech profits surged 110%, and Shanghai sold the sector anyway
NBS data showed industrial profits up 15.7% year-on-year through August, with tech manufacturing profits surging roughly 110%. Shanghai and Shenzhen sold the sector anyway after the holiday, pricing chip-access risk from last week's Trump-Xi summit over the earnings.

That's your daily macro roundup. For more detailed regional deep dives, check out our weekly editions. If you found this useful, feel free to forward it along. More signal, less noise, as ever. Cheers.
Discussion